Wall Street's fear gauge may be flashing a buy sign
In this article
.VIX
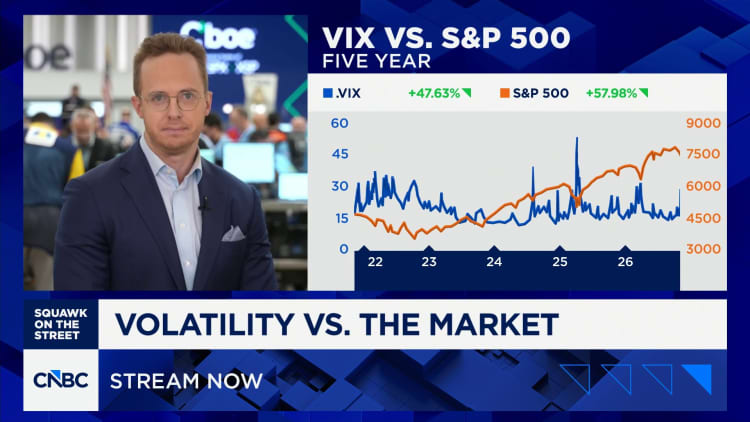
watch nowVIDEO2:4202:42Options Action: Volatility vs. the marketOptions ActionThere's nothing like a good selloff to turn a trader into an investor – so the saying goes. It's an adage that echoes the sentiment of an even older one: buy when there's blood in the streets.
The maxims ring true after Thursday's selloff in stocks that sent the Cboe Volatility Index (VIX) to its biggest one-day move since April 2025's "Liberation" week for tariffs, according to data from Bespoke Investment Group.
In the 19 instances since 1990 in which the VIX rose at least five points from under 20 – it surged more than 11 points from 16.6 to 28.2 Thursday – the median return for the S&P 500 Index three months later was 4.2%, and 4.8% six months later, according to Bespoke analysis that also showed returns were positive 68% and 79% of the time over each period, respectively.
"These types of sharp spikes from placid levels are like a line of thunderstorms coming through in summer," said Paul Hickey, co-founder of Bespoke. "The sky quickly darkens and wind gusts, but the loudest thunder and brightest lightning doesn't last long."
Cboe Volatility Index, YTDTo be sure, the data do show the storms can be disruptive near-term. While the median return one month after such events was 2.1%, the average return was negative 0.4%, thanks to a few big downdrafts following volatility surges in 1990 and more recently, Feb. 24, 2020, when the Covid selloff was just getting started.
According to X account OddStats, there were only 12 other days in stock market history prior to Thursday when the S&P 500 lost 4% and the Nasdaq 100 Index lost 6% – including one during Liberation week 2025 and three instances during the 2020 pandemic.
Tech volatility was even more pronounced as the Nasdaq 100 posted its worst day since March 2020. The Cboe Nasdaq Volatility Index VXN jumped more than 13 points to 38.3, the highest since April 11, 2025.
The selling was so intense in chipmakers that the VanEck Semiconductor ETF (SMH) traded below its net asset value. Yet options traders were still leaning bearish in their trades into the bell Thursday, with 670,000 puts traded out of the total 900,000 options on the ETF. Of the total $1.7 billion options premium exchanged, $1.5 billion of it was in puts, according to SpotGamma.
Choose CNBC as your preferred source on Google and never miss a moment from the most trusted name in business news.